Air Service One talks with…. Ioanna Papadopoulou, Director Communications & Marketing at Athens International Airport
Athens International Airport is continuing its strong growth, supported by international demand, new airlines and routes, and an increasingly balanced year-round traffic profile. At the same time, the airport is looking beyond its traditional European markets, with further long-haul growth in North America, Asia and other underserved regions on the agenda, while a major infrastructure expansion programme is being rolled out to accommodate future demand.
Air Service One sat down with Ioanna Papadopoulou, Director Communications & Marketing at Athens International Airport, to discuss the airport’s performance, network development priorities and plans for the years ahead.
Athens Airport has seen strong passenger growth over the past few years. What are your expectations in 2026?
Athens International Airport entered 2026 with a very strong momentum, following a record-breaking 2025 during which passenger traffic reached almost 34 million, exceeding pre-pandemic levels by almost 33% and confirming Athens’ global position as one of Europe’s strongest-performing major airport markets. In 2026, growth is driven by strong international demand, with new airlines, new markets and new routes already added in the airport’s network.
During the first 8 months of the year, this positive trajectory continues despite the volatile geopolitical situation affecting the wider region. The 2026 performance also confirms that Athens’ traffic base is becoming less dependent on the traditional summer peak, with strong volumes extending across more months throughout the year and reinforcing the airport’s progress towards a more balanced year-round demand pattern. On this basis, AIA is on track to close 2026 with another all-time passenger record, allowing Athens to maintain the position it has achieved in recent years among the top European airports in terms of growth.
Have you seen any impact because of the ongoing fuel crisis?
So far, the impact has been contained rather than structural. The initially sharp increase in fuel prices briefly created pressure and concerns for airlines, particularly because jet fuel prices increased faster than crude oil, and this translated into fare adjustments and temporary operational disruption on certain Middle East and Gulf routes. Greek carriers reacted cautiously, by limiting fare increases to single-digit levels on selected routes, supported by their fuel-hedging strategy, as well as by running substantial promotions and travel deals.
From a demand perspective, the fundamentals remain positive, with the Athens’ market having demonstrated notable resilience. Tourism expectations for 2026 remain in growth territory, the wider European travel market is still expanding, and scheduled flights at Greek airports for the May – August period were up around 3.6%, compared with about 1.6% across Europe. This indicates that, after a short slowdown during the early days of the disruption, the market quickly regained momentum, supported by Greece’s strong positioning in European leisure demand.
Which markets are currently generating the highest levels of unserved or underserved demand?
With Athens already connected to more than 100 European destinations, it is expected that the most substantial unserved and underserved opportunities now point increasingly towards long-haul markets. The data clearly confirms this. In North America, Los Angeles stands out as the largest unserved opportunity, followed by San Francisco, while additional unserved demand is visible from Miami, Houston, Vancouver, Seattle, Detroit and Denver. At the same time, several major North American operated hubs remain clearly underserved with room for additional capacity on a year-round basis, including Chicago, Boston, Washington Dulles, as well as Atlanta, Dallas–Fort Worth and Charlotte.
China is also a market with great potential. With direct connections to Beijing and Shanghai, we are very optimistic for the development of additional direct services, from a substantial number of Chinese cities in the near future.
Australia is another market with strong strategic relevance, also because of the vibrant Greek diaspora, while the rest of Asia also demonstrates significant potential, with more than half a million indirect passengers in total, across key markets such as Singapore, Seoul, Manila, Tokyo, Bangkok, Lahore, Dhaka and Hong Kong.
Finally, although Athens does not yet have direct service to South America, we see meaningful indirect volumes from origins such as São Paulo, Rio de Janeiro and Mexico, confirming the broader long-haul opportunity for Athens beyond the currently served network. Overall, there are tremendous route development opportunities: Athens has both sizeable unserved long-haul demand and a number of markets where existing capacity can be further developed, supporting our mid -and long- term goal for the increase of long-haul, year-round connectivity and our focus on stronger global reach for Athens and Greece.
Which recent route launches have exceeded your expectations in terms of passenger performance and airline interest?
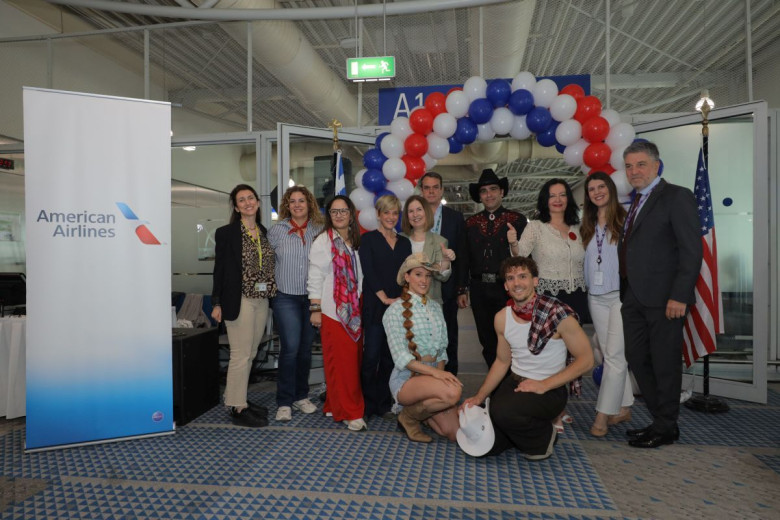
Several recent route developments underline the strong airline interest in Athens and the confidence in the market’s performance. All our US routes are performing exceptionally well. Talking about the most recent developments, a major highlight is American Airlines’ direct service between Dallas–Fort Worth and Athens, which, in 2026 opened an important new gateway to the United States and connected Athens with one of the world’s largest airline hubs, further strengthening our North American connectivity.
Among other developments, perhaps the most exciting one this year, is the launch of the direct connection between Athens and India, with IndiGo having commenced operations at the end of January 2026 – connecting Athens to Delhi and Mumbai – the first-ever direct air connection between Athens and the Indian market. IndiGo’s decision to deploy its newly delivered Airbus A321XLR aircraft underlines the significance and potential of this market, opening important opportunities for tourism, trade and cultural exchange.
As far as the European routes are concerned, TAP Air Portugal’s commencement of operations from/to Lisbon has been a highly important development, and is substantially stimulating passenger traffic between Greece, Portugal and beyond.
Athens has experienced significant expansion in the North American market. How would you assess the performance of services to the United States and Canada?
North America has been one of the most spectacular success stories for Athens in recent years. In the United States market, weekly summer frequencies have increased from 46 in 2019 to 103 in both 2025 and 2026, representing growth of around 124% versus pre-pandemic levels. At the same time, the US network has expanded from four airport destinations in 2019 to nine today, supported by five airlines and a much broader geographic footprint across New York JFK, New York EWR, Chicago, Philadelphia, Atlanta, Boston, Washington, Charlotte and, from 2026, Dallas–Fort Worth.
Canada has also become an important part of this growth story, with direct summer services to Toronto and Montreal further strengthened in 2026, reaching close to 30 weekly frequencies, through the addition of weekly frequencies and the already announced extension of services up to January 2027, by Air Canada.
The demand fundamentals are equally strong: the United States remain Athens’ leading long-haul source market, with arrivals continuing to grow. During January–July 2026, U.S. arrivals demonstrated an increase of 6% year-on-year, following strong growth in previous years. Overall, the performance confirms that North America is a core pillar of the airport’s international network and one of the strongest drivers of inbound tourism to Greece.
Are there still major North American cities that Athens Airport believes could support nonstop flights?
Yes, and the underlying demand data confirms that there is still room for further North American growth. As previously mentioned, Los Angeles remains the largest unserved opportunity, followed by San Francisco. Other meaningful indirect flows are also visible from Miami, Houston, Vancouver, Detroit, Denver and of course Seattle, which is now becoming a landmark example of how this demand can be converted into nonstop connectivity. Alaska Airlines is making history as the first airline to announce nonstop services from Seattle to Athens. The seasonal route will begin on 12 May 2027, will operate three times per week and it will be the longest route Alaska has ever flown. When launched, it will also be the West Coast’s only nonstop Athens service, making access to Greece and onward destinations significantly easier for travellers across the region. This development clearly validates the strength of Athens’ North American long-haul opportunity and reinforces our confidence that further West Coast growth can be supported over time. Beyond new city pairs, there is also clear potential for further enhancement of already-served routes with strong passenger demand, with major hubs such as Chicago, Atlanta and Dallas–Fort Worth offering scope to evolve beyond seasonal operations and potentially support year-round services in the future.
Athens has traditionally served as a gateway between Europe and Asia. How important is restoring and expanding Asian connectivity?
Restoring and expanding Asian connectivity is a strategic priority for Athens. The fundamentals are strong: there is significant Asian demand out of ATH, but direct services remain rather limited, a fact which points to a clear opportunity for new long-haul connectivity. The unserved demand data highlights this clearly, with strong indirect volumes from several cities in China and Asian markets such as Guangzhou, Shenzhen, Xi ‘An, Manila, Seoul, Bangkok, Tokyo and Hong Kong. At the same time, the wider relationship between Greece and Asian markets is being strengthened across several areas, including business, product imports, maritime activity and shipping, all of which support a broader base of travel demand beyond leisure alone.
Athens is also very well positioned geographically as the first EU entry point from the East, offering strong connectivity potential from South-East Asia and Australia to Europe, as well as, vice versa, from Europe and the wider Balkan region to Australasia. In the case of South Korea & China there is also clear strategic momentum, with the Greek Government and the Greek National Tourism Organization actively working with tour operators and international stakeholders to attract more visitors, reinforcing why Asian connectivity is so important for Athens’ next stage of growth.
On our part, we are substantially supporting these opportunities with robust incentive schemes and marketing support programmes for new long-haul routes.
Low-cost carriers account for a notable share of traffic at Athens Airport. How do you balance LCC growth with network carrier development?
Athens has developed a very balanced airline ecosystem. In 2025, the airport was served by 70 airlines, of which 27 were low-cost carriers. This is an important part of our growth story, but at the same time, the market is well diversified, with no single airline or business model dominating excessively.
The Greek home-based carriers account for almost 55% of our traffic, the low-cost carriers somewhat less than 20%, and all other carriers around 26-27%. This creates a healthy balance between a strong home-carrier base, full-service network carriers, hybrid operators and low-cost airlines.
Our approach is therefore not to prioritise one model over another, but to support sustainable growth across all segments irrespective of their business model and mode of operations. Our rich portfolio of non-discriminatory and transparent incentives and our strong and diversified marketing strategy form a marketing “tool-kit” aiming at supporting all airlines operating to Athens.
The combination of full-service carriers, low-cost carriers, hybrid operators, and a growing portfolio of long-haul airlines, along with a geographically diversified traffic base across Europe, North America, the Middle East and Asia-Pacific, is a balanced mix which supports resilience, competitiveness and year-round growth.
Passenger traffic continues to set new records. How is Athens Airport preparing for future capacity requirements?
To support the next phase of growth, Athens International Airport is implementing a major expansion programme designed to substantially increase annual capacity. This investment responds directly to the airport’s sustained traffic growth, with Athens International Airport having handled almost 34 million passengers in 2025 and continuing to rank among Europe’s strongest-performing major airports.
The project aims at significantly enhancing the airport’s infrastructure and substantially elevating the overall passenger experience. Additionally, works for the development of 32 additional aircraft stands, and a new multi-storey car park providing more than 3,300 additional parking spaces have already commenced, as well as a wide range of passenger-experience improvements aimed at increasing efficiency and reducing congestion.
Beyond addressing capacity needs, the programme is a strategic enabler for the airport’s and the city’s future development, also aiming at maximising the airport’s economic, tourism and societal contribution at a local, regional and national scale.